
Since April 2026, Adobe has been in a holding pattern, posting a small return of 3.1% while floating around $254.84. The stock also fell short of the S&P 500’s 8.9% gain during that period.
Is there a buying opportunity in Adobe, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is Adobe Not Exciting?
We’re cautious about Adobe. Here are three reasons why there are better opportunities than ADBE, plus one stock we’d rather own.
1. Weak Billings Point to Soft Demand
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
Adobe’s billings came in at $6.71 billion in Q3, and over the last four quarters, its year-on-year growth averaged 11.9%. This performance was underwhelming and suggests that increasing competition is causing challenges in acquiring/retaining customers. 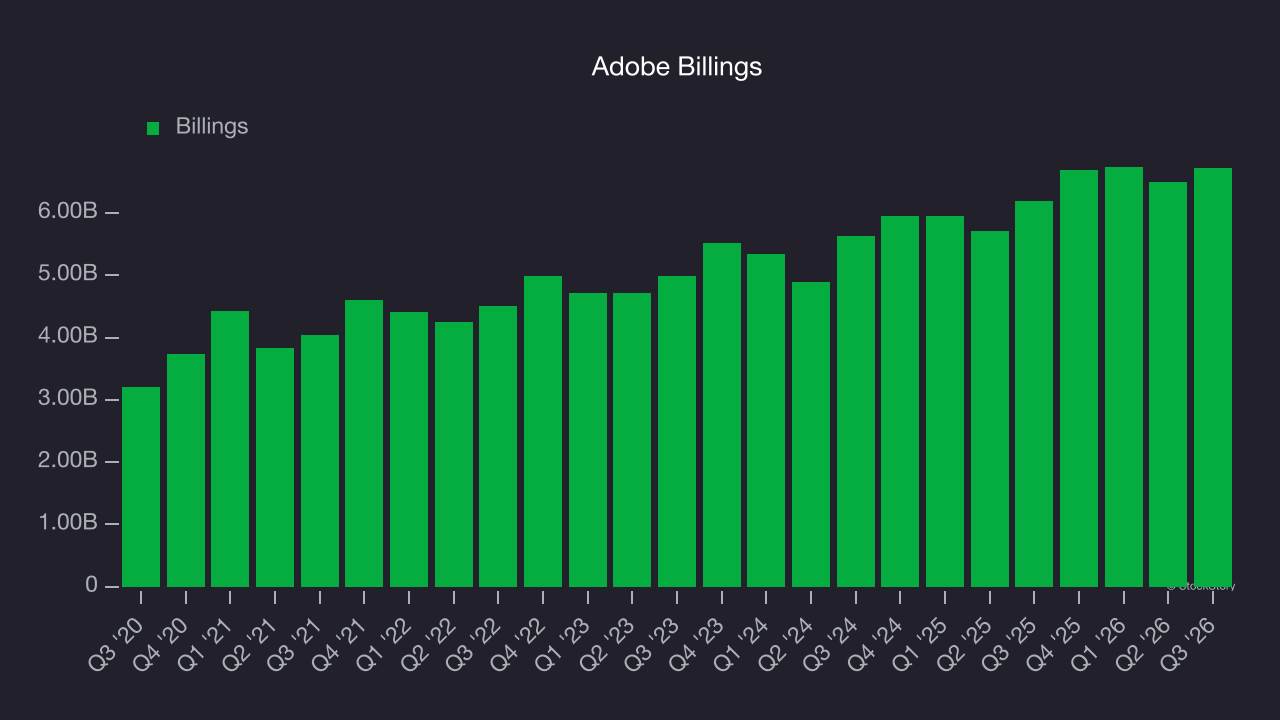
2. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Adobe’s revenue to rise by 9.3%, a slight deceleration versus its 11.5% annualized growth for the past five years. This projection doesn’t excite us and indicates its products and services will face some demand challenges.
3. Operating Margin in Limbo
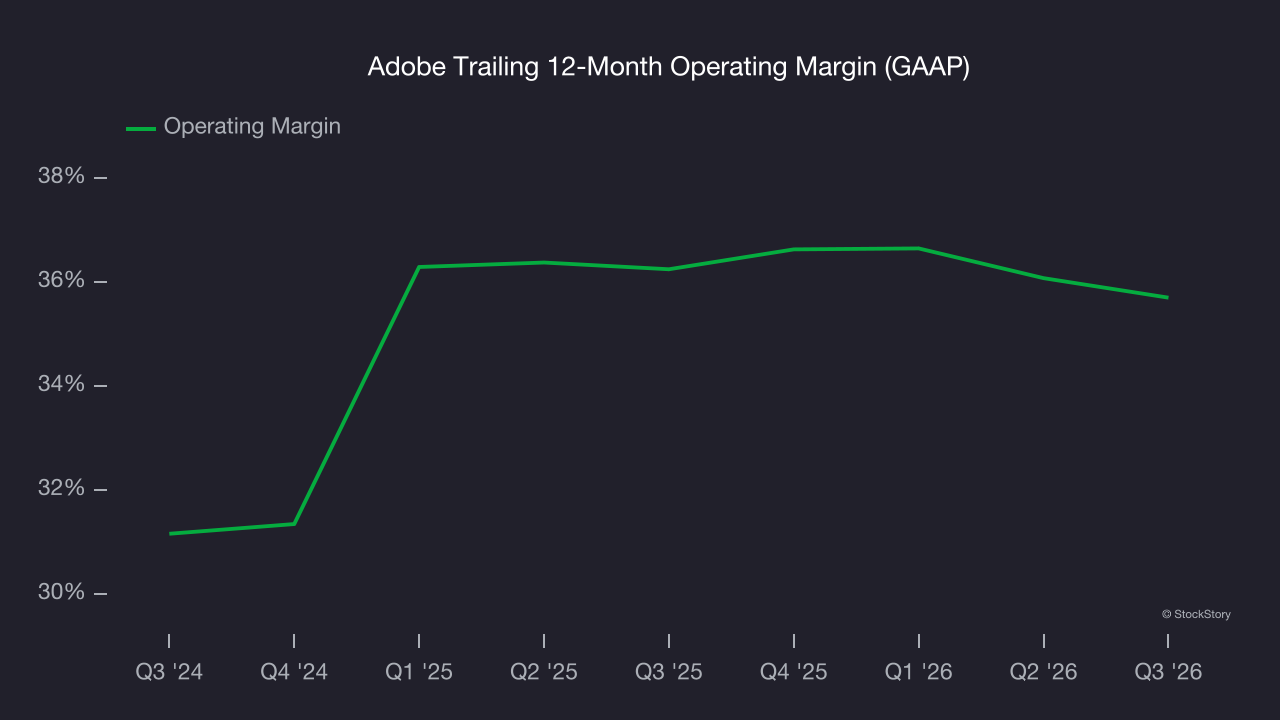
While many software businesses point investors to their adjusted profits, which exclude stock-based compensation (SBC), we prefer GAAP operating margin because SBC is a legitimate expense used to attract and retain talent. This is one of the best measures of profitability because it shows how much money a company takes home after developing, marketing, and selling its products.
Analyzing the trend in its profitability, Adobe’s operating margin might have fluctuated slightly but has generally stayed the same over the last two years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its operating margin for the trailing 12 months was 35.7%.
Final Judgment
Adobe’s business quality ultimately falls short of our standards. With its shares trailing the market in recent months, the stock trades at 3.4× forward price-to-sales (or $254.84 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re fairly confident there are better investments elsewhere. We’d suggest looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
Stocks We Would Buy Instead of Adobe
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.